Plan your retirement on UK rules, from the State Pension to your ISA
Start PlanningSet your plan to the United Kingdom and Ready Aim Retire plans with the rules you actually live under: your workplace pension and SIPP, your ISAs and General Investment Accounts, the State Pension, income tax and National Insurance, and a tax year that starts in April.
It shows how each pound you draw is taxed, month by month, to the end of your plan. And we tell you plainly which UK rules it includes, and which it leaves out.
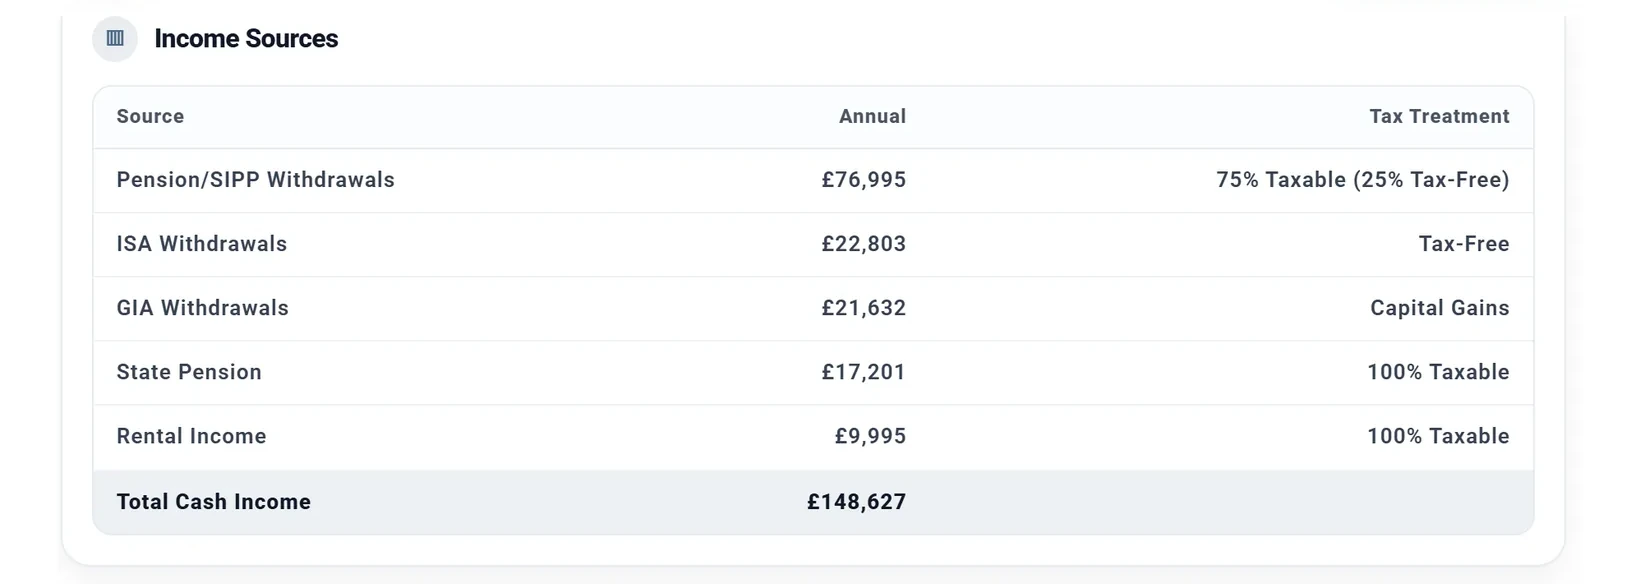
The year Chris turns 67, in Tax Details. Chris and Jamie are a made-up couple we use in our examples.
Every new plan starts in the United States. Open Location in your profile and choose United Kingdom, and the planner switches to UK tax rules, the State Pension and UK account types. Nothing changes until you confirm.
What the switch does:
One thing to know: the switch keeps every number as it is, so $650,000 becomes £650,000. Enter your balances, spending and income in pounds.
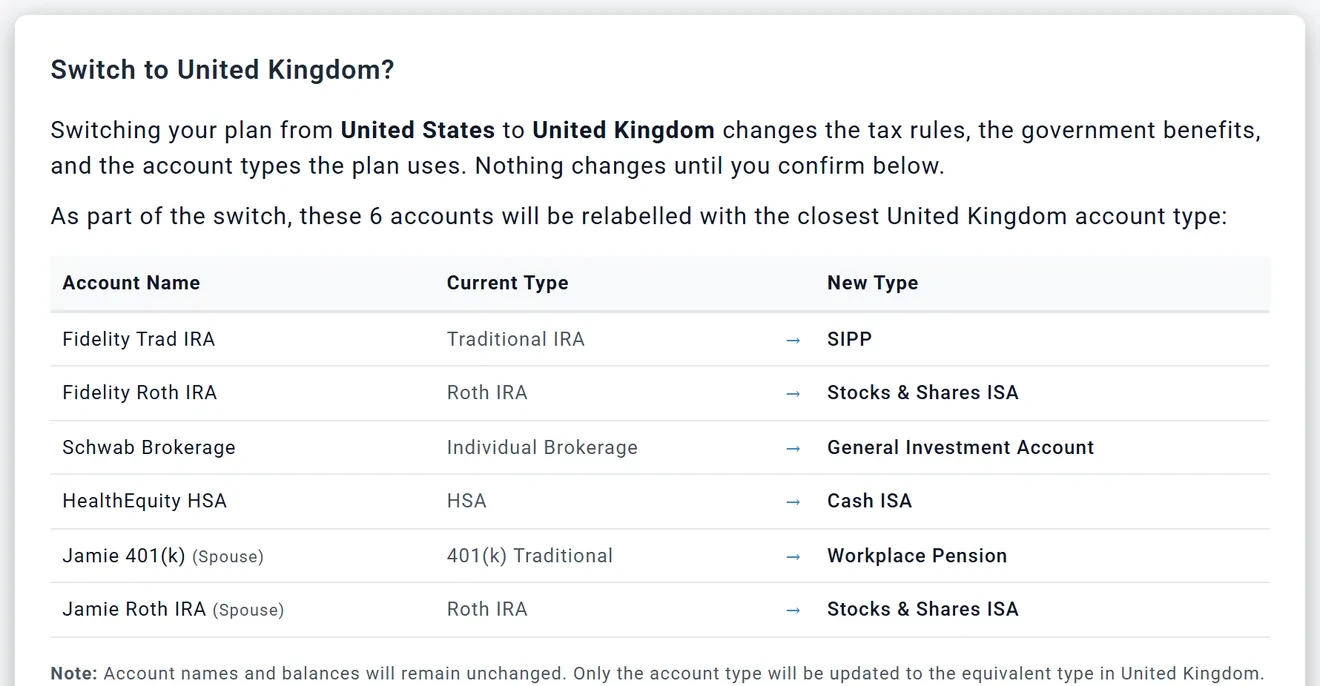
Chris and Jamie's accounts on the way to the UK.
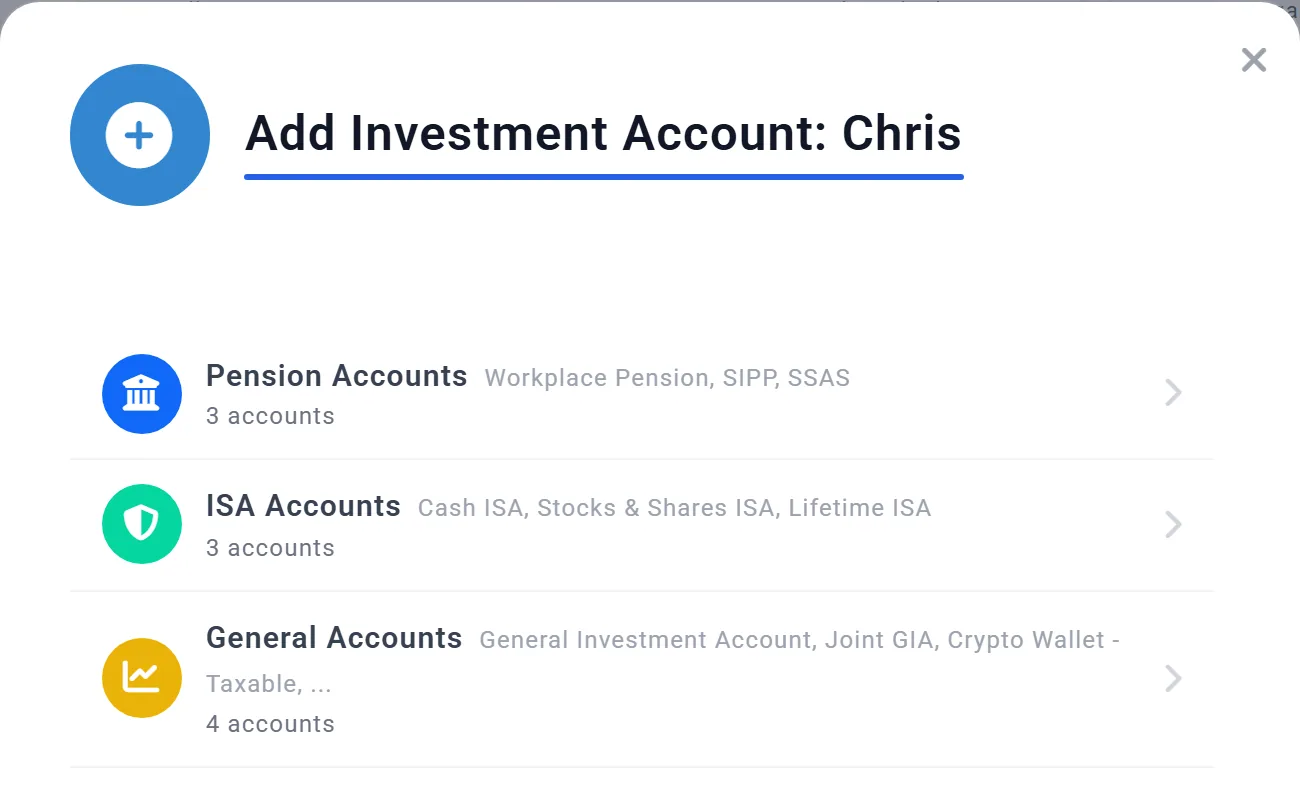
The account types in a UK plan.
A UK plan offers the accounts you actually hold. Here is how each kind is taxed when you draw from it:
Saving follows the rules too. Your plan applies the £60,000 pension annual allowance and the £20,000 ISA allowance, with up to £4,000 of it in a Lifetime ISA and its 25% bonus. Money over an allowance isn't lost: pension money lands in cash, and ISA money goes to your General Investment Account.
Enter the amount from your State Pension forecast on gov.uk, for you and, in a couple's plan, your spouse. There is no National Insurance record to fill in.
A pension that pays you an income, from an employer or a final salary or career average scheme, has its own box, and is taxed as income too.
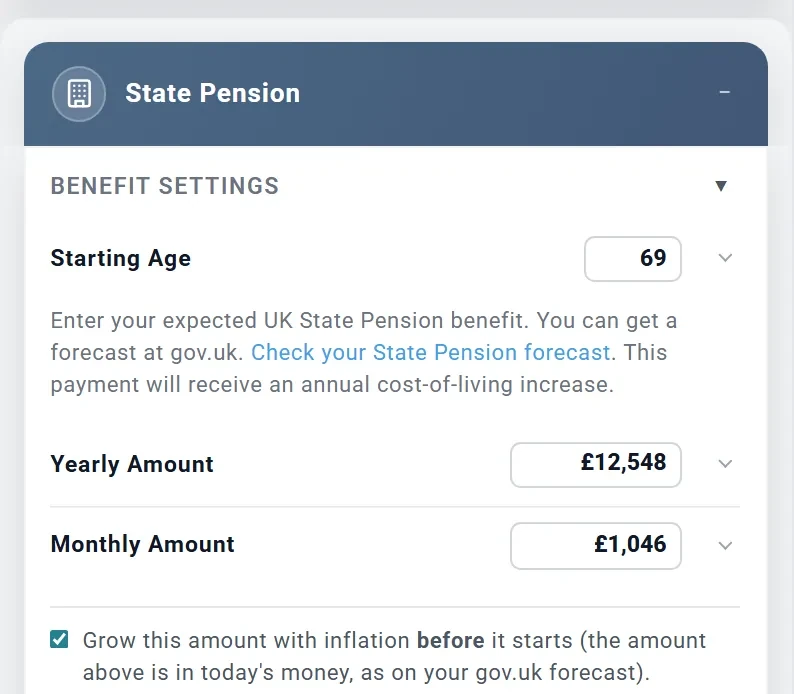
£12,548 a year is the starting example. Replace it with your own forecast.
Your tax uses the 2026/27 bands and rates:
A couple is taxed as two people, each with your own allowance, bands and exemption.
The UK tax year starts on 6 April. Your plan works in whole months, so its tax year runs from April to March. Each April:
At the end of each year, the plan works out the tax on the year's actual income and settles the difference. Your Taxes can show every figure by tax year, labeled 2030/31 and so on.
With Planner+, the Estate tab adds a UK Inheritance Tax panel. It prices the last death with:
From the 2027/28 tax year, your pensions count in the estate too.
In place of Roth conversions, which are a US idea, the Optimizer tests every withdrawal order with extra pension withdrawals in low-income years. They fill the 20% basic-rate band, or go on toward the higher-rate band, and stop at the £100,000 point where your Personal Allowance starts to fall. In a couple's plan, it fills each person's band separately.
The whole plan follows the pension rules:
Social Security, Medicare, marketplace health insurance and Roth conversions are US features, so a UK plan doesn't show them. A few UK rules aren't modeled yet:
A few screens still show a $ sign. The amounts are your plan's pounds.
A UK plan uses the tax rules and allowances described above, and simplifies UK pension tax for planning. Tax law, returns and your own life will differ, so check your State Pension forecast on gov.uk and keep your plan up to date. Ready Aim Retire is an educational tool, not tax, pension or investment advice.
Your plan in plain English, and what is worth a look next.
Your plan replayed through real market history since 1871.
Every year of your plan, and the milestones that shape it.
See your financial progress clearly and over time.
Searches withdrawal orders and Roth conversions for a better strategy.
Pay for retirement in the order that keeps more of your money.