Understand how resilient your retirement plan really is
Retirement planning isn't about predicting the future perfectly. It's about understanding how well your plan holds up when the future doesn't cooperate.
Ready Aim Retire's Chance of Success replays your whole plan through real US market history since 1871: once starting in 1871, once in 1872, and so on, every month in the order it happened. Nothing is random, so the same plan gives the same answer every time.
Start PlanningMarkets don't move in straight lines.
Each trial starts your plan today and runs it through the markets of one start year onward, through your working years and your retirement. The 1929 trial is your plan from this month on, with the markets of January 1929 onward. Each trial lives with its own era's inflation too, for your spending, Social Security and tax brackets.
How it works:
With Planner+, the Portfolio chart shows how your savings spread across every trial, year by year.
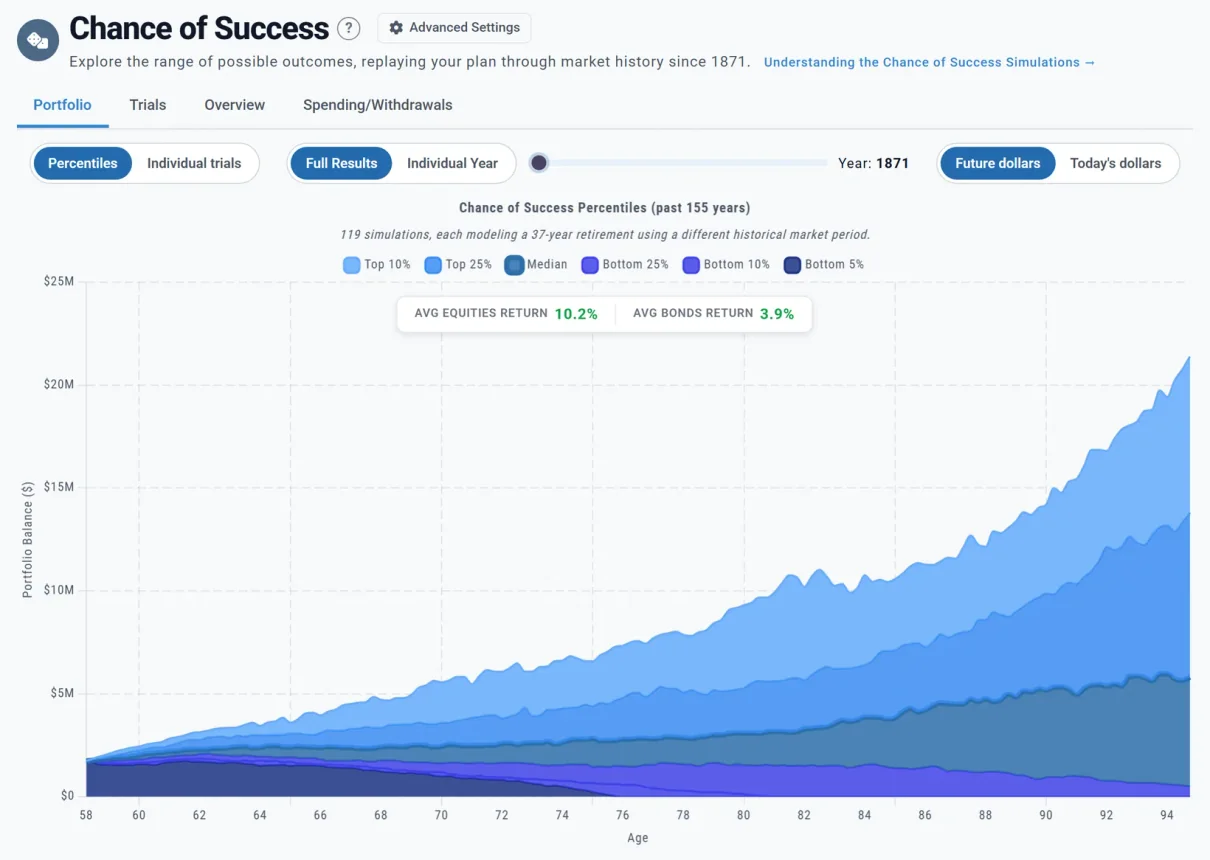
Every trial at once, from the top 10% to the bottom 5%. Chris and Jamie, a made-up couple, with their spending raised to $12,000 a month.
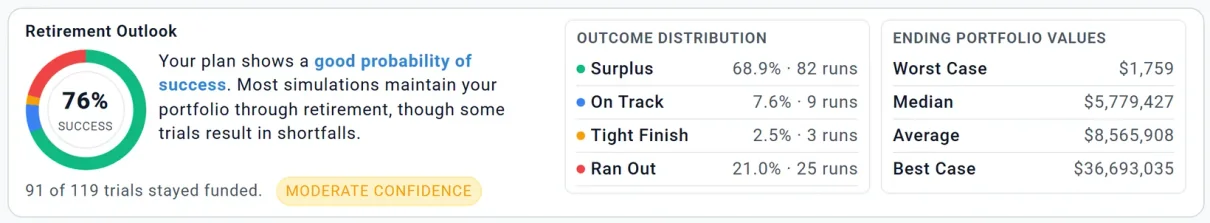
Chris and Jamie's Retirement Outlook at $12,000 a month: 91 of their 119 trials stay funded.
Your Chance of Success is the share of trials in which your plan never ran out. There is no button to press: it runs when you open the tab, and again whenever you change your plan.
The Retirement Outlook puts the evidence beside it:
A trial that ends with $1 counts the same as one that ends with millions, so read the bands, not just the percentage. Your Summary and your Dashboard show the same result.
A plan doesn't have to spend the same amount through a crash. Guardrails make a small cut after a fall and a small raise after a rise, always within limits. Switch them on in Advanced Settings and pick a style.
Three styles:
Only your lifestyle spending moves. One-time costs, milestone expenses, insurance premiums and taxes are never cut. At $12,000 a month, Balanced guardrails take Chris and Jamie from 91 to 115 of their 119 trials.
Guardrails apply to Chance of Success only, in Monthly Expenses mode. Your Dashboard keeps your planned spending.
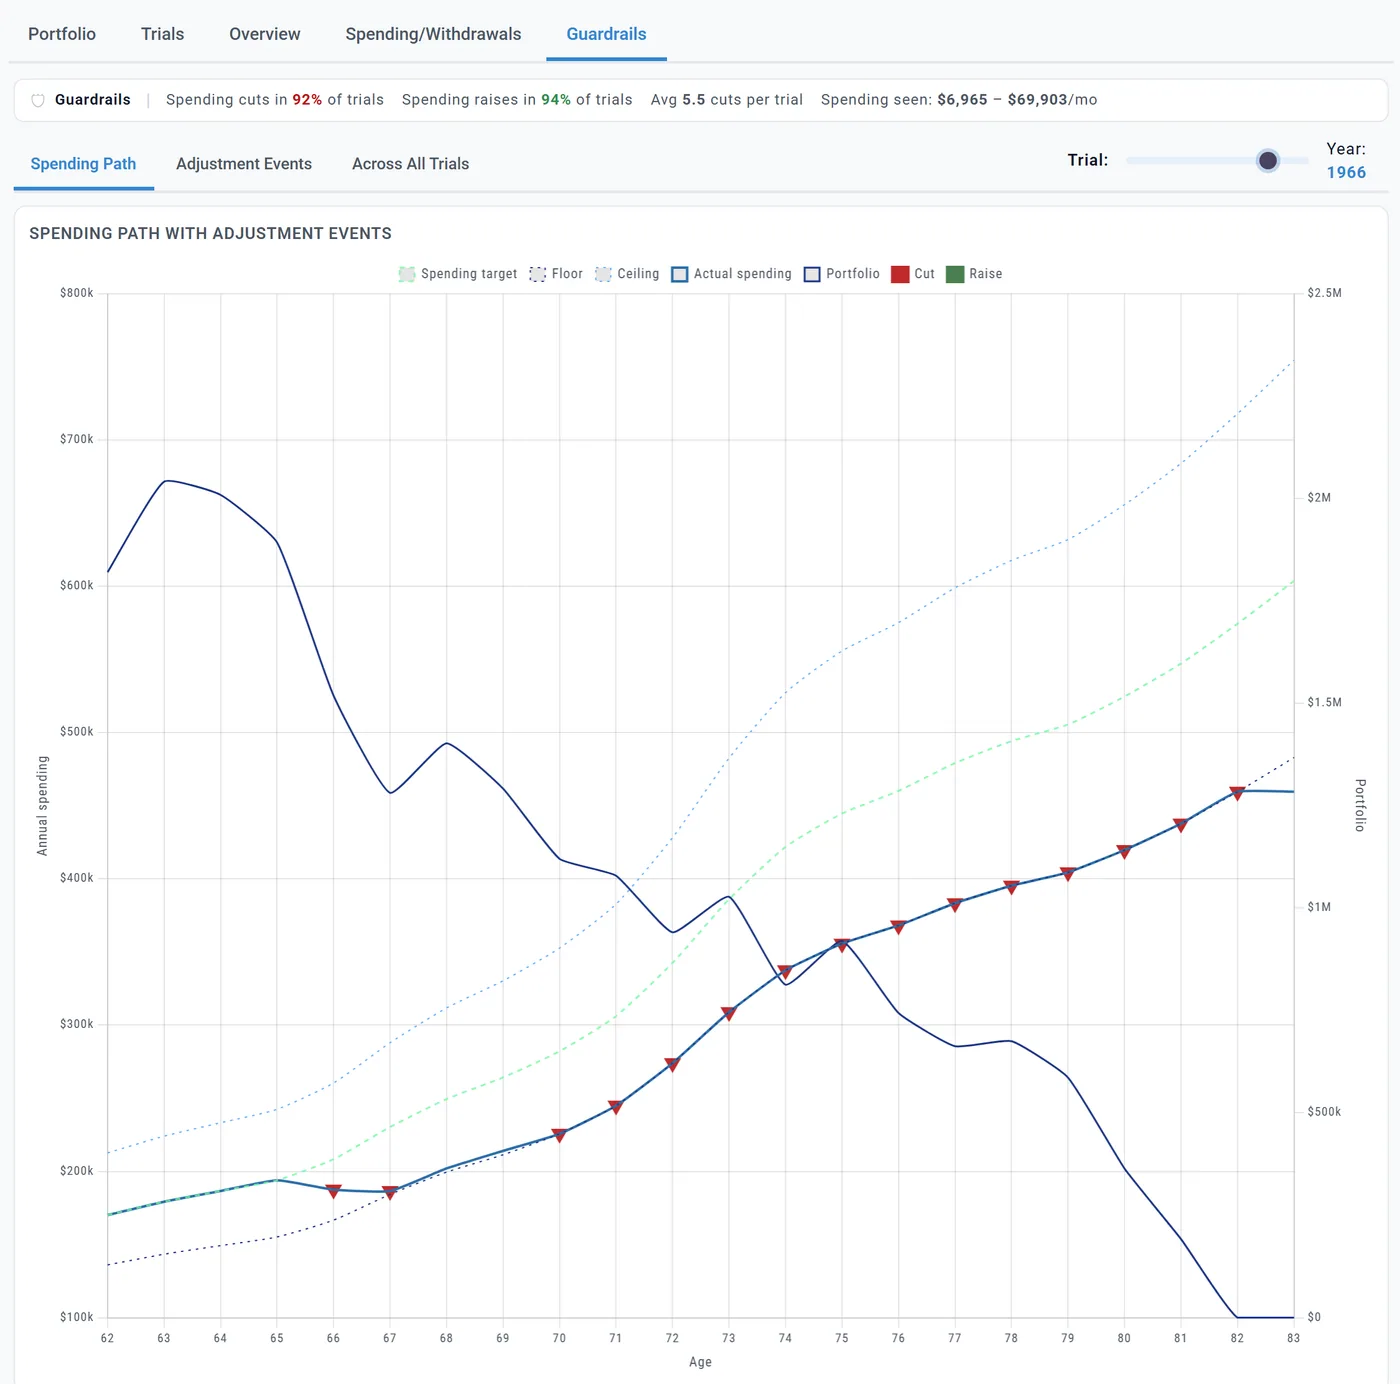
Chris and Jamie's 1966 trial with Balanced guardrails: cuts at 66, 67 and every year from 70 make the money last to 82 instead of 74.
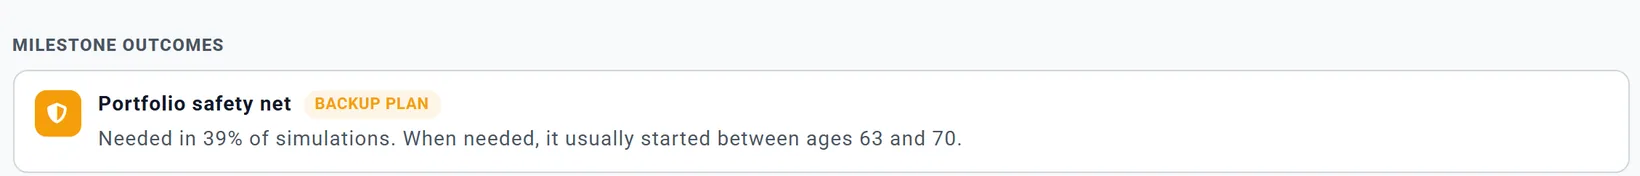
Chris and Jamie never need their safety net in their projection. Across market history, they need it in 39% of trials.
A milestone can watch your savings: "portfolio reaches $2 million", or a backup plan such as part-time work if savings fall below $1.5 million. Each market history decides for itself whether, and when, it happens.
Under the Retirement Outlook, each one gets a card:
To see what a backup plan is worth, note your Chance of Success, switch the milestone off in What's Counted, and compare.
1929, 1966, 2000 and 2008 are all in the data. A start year is the year your plan starts, not the year you retire.
So to test a crash you would retire into:
No made-up crashes: stress testing here uses real history.
Your Dashboard shows one projection, at the returns and inflation you entered, the same every year. Chance of Success is the only place that uses market history.
Both are right about what they measure:
The Dashboard puts the two side by side, so you see both.
Chance of Success isn't about chasing 100%. It's about making informed adjustments.
Change your plan and the result updates:
Spending Sensitivity Analysis finds the most you could spend each month and still keep a 95%, 90%, 85% or 80% chance of success.
The Simulation range in Advanced Settings sets the first and last years the trials can use. Until you move it, your plan follows the newest data. Pull the handles together and it runs a single trial.
Planning in Canada or the UK? The trials use the same US market history and US inflation, and guardrails check at the start of your tax year: January in Canada, April in the UK.
Switch to Today's dollars and each trial is converted with its own history of prices, so a 1970s trial is deflated by 1970s inflation.
The ending values and charts change. Your Chance of Success, the outcome bands and the trial counts do not, because success is judged on the actual dollars.
Chance of Success shows how your plan would have fared in US market history since 1871. It does not predict the future. Trials that start a year apart share most of their years, so treat percentages a few points apart as the same. Ready Aim Retire is an educational tool, not financial or investment advice.
Your plan in plain English, and what is worth a look next.
Ask about your plan in plain English, and get answers from your own numbers.
Every year of your plan, and the milestones that shape it.
See your financial progress clearly and over time.
Searches withdrawal orders and Roth conversions for a better strategy.
Pay for retirement in the order that keeps more of your money.